What a 571 sq ft flat at Devanahalli actually rents for
Almost every investment pitch on this corridor quotes a rental yield without quoting a rent. The rent is the part that can be checked, so start there.
The short answer
A one bedroom flat at Devanahalli currently lets for roughly ₹19,000 to ₹25,000 a month, with listing averages around ₹23,000 as of mid 2026. The micro-market gross yield sits near 3.4 per cent.
On a Prestige Parklane 1 BHK, that is a gross yield of about 3.3 to 4.1 per cent on the full cost to own. Net of maintenance and a month's vacancy, it is closer to 2.6 to 3.3 per cent. The larger variable is not the rate. It is that Parklane will complete 858 identical one bedroom flats at broadly the same time, and they will compete with each other.
What one bedrooms actually rent for today
Today's Devanahalli rental market is small and thinly listed. That is itself informative. Listing platforms carry a few dozen one bedroom flats at any time, at roughly ₹19,000 to ₹25,000 a month. Reported averages sit near ₹23,000 in mid 2026, and micro-market yield runs at about 3.4 per cent. Corridor rate and trend data is published here.
Two cautions apply before you build anything on those numbers. Listing rents are asking rents, not achieved rents. In a thin market the gap between the two is wider than in a deep one. And today's scarcity is doing work in that number. There is very little modern one bedroom stock at Devanahalli, so the few units available are not competing hard.
The yield, worked through
Start from the real cost, not the headline. The Parklane 1 BHK starts at ₹65 lakhs, all inclusive. Add about ₹2.56 lakhs of possession charges and ₹4.88 lakhs of registration at 7.5 per cent, and the total to own is about ₹72.4 lakhs.
| Monthly rent | Annual gross | Gross yield on ₹65 L | Gross yield on ₹72.4 L all in |
|---|---|---|---|
| ₹18,000 | ₹2.16 L | 3.3% | 3.0% |
| ₹20,000 | ₹2.40 L | 3.7% | 3.3% |
| ₹23,000 | ₹2.76 L | 4.2% | 3.8% |
| ₹25,000 | ₹3.00 L | 4.6% | 4.1% |
Quote the all-in column, not the headline one. Registration and possession charges are real money you do not recover at exit.
From gross to net
Now take the costs out. Three matter most.
- Maintenance. The fact sheet's advance CAM works out at ₹5 per sq ft a month. On 571 sq ft that is about ₹2,855 a month, paid by the owner.
- Vacancy. One month a year is a normal assumption, not a pessimistic one.
- Tax. Rent is taxable at your slab, after a 30 per cent standard deduction.
| Monthly rent | Net before tax, 11 months less maintenance | Net yield on ₹72.4 L |
|---|---|---|
| ₹18,000 | ₹1.64 L | 2.3% |
| ₹20,000 | ₹1.86 L | 2.6% |
| ₹23,000 | ₹2.19 L | 3.0% |
| ₹25,000 | ₹2.41 L | 3.3% |
On the middle case, ₹23,000 a month, the net before tax is about ₹2.19 lakhs a year. That is roughly 3.0 per cent on the all-in cost. It is a real number, and not a bad one for Indian residential, which has run at 2 to 4 per cent for years. It is simply not the 5 or 6 per cent that gets quoted in sales conversations.
If you borrowed to buy: the monthly cash gap
Yield assumes you paid cash. Most investors borrow, and then the question that matters is not yield. It is how much you top up each month. Take an 80 per cent loan of ₹52 lakhs at 7.75 per cent over 20 years. The EMI is about ₹42,689. Add maintenance of about ₹2,855.
| Monthly rent | Rent covers of the EMI | You fund each month | You fund each year |
|---|---|---|---|
| ₹18,000 | 42% | About ₹27,544 | About ₹3.31 L |
| ₹20,000 | 47% | About ₹25,544 | About ₹3.07 L |
| ₹23,000 | 54% | About ₹22,544 | About ₹2.71 L |
| ₹25,000 | 59% | About ₹20,544 | About ₹2.47 L |
In a vacant month there is no rent at all, so you fund the full ₹45,544. That is the honest shape of a leveraged 1 BHK here. Rent covers roughly half the EMI. The other half comes from your salary for years.
It can still be a sound purchase. But it is a monthly commitment of ₹20,000 to ₹28,000, not a self-funding asset. Budget it as one. Stress test it too. Ask whether you could carry that top-up for a full year if your own income dipped.
What would make it self-funding
Only a much larger down payment, or a much higher rent than the corridor supports today. To cover the EMI and maintenance from rent alone at ₹23,000, the loan would need to be roughly half its size. That means putting in closer to 60 per cent of the price yourself.
The part nobody models: 858 of them at once
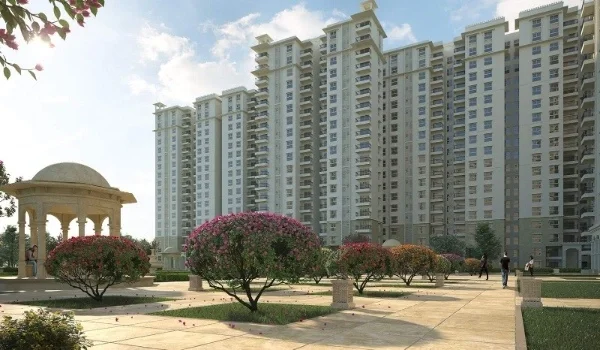
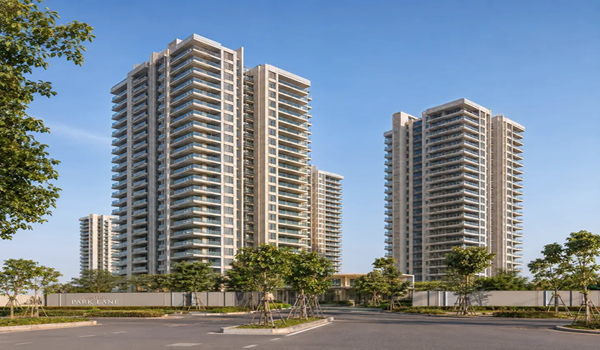
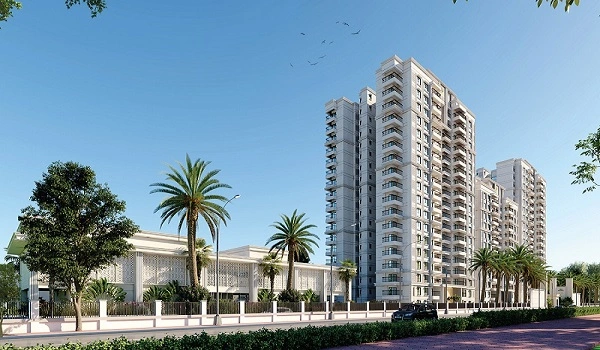
This is the argument that matters, and it barely appears anywhere. Prestige Parklane has a single one bedroom layout at 567 to 571 sq ft, repeated 858 times across nine towers. The RERA filing confirms the count. That is 48 per cent of the project.
Those units complete together, against a declared completion date of 31 December 2030. If even 40 per cent are bought to let, roughly 340 identical flats reach the rental market in the same window. They sit in the same nine towers, with the same layout, the same finish and the same view of the same park.
A tenant comparing 340 interchangeable flats has pricing power. There is no differentiation to pay a premium for. The rent then is not set by what one bedrooms fetch today in a market with a dozen listings. It is set by what 340 landlords will accept rather than hold an empty flat.
That does not mean the rent collapses. It means the scarcity premium in today's ₹23,000 is unlikely to survive completion. A model built on today's listing average is optimistic by an amount you should size for yourself. Run it at ₹18,000 as well as ₹23,000.
Who actually rents these
The bull case for this unit mix is the employment on the same land. It is worth being precise about which part of that employment can pay the rent.
| Tenant | Can they pay ₹20,000 plus? | Notes |
|---|---|---|
| Manufacturing line and assembly staff | Generally no | Rent would be a large share of pay. This cohort shares accommodation or lives further out. |
| Engineers and supervisors at the aerospace and electronics units | Yes | The core tenant for this product |
| Airport and airline staff, hospitality management | Often yes | Shift patterns make proximity genuinely valuable |
| Young couples and single professionals | Yes | Smallest group today, grows as social infrastructure arrives |
The headline employment numbers on this corridor, tens of thousands of jobs, are not all addressable demand for a ₹20,000 flat. The addressable slice is the salaried professional layer, a fraction of the total. It is a real and growing fraction, and it is smaller than the headline suggests.
How to underwrite this honestly
Model the rent, not the yield. A yield percentage is an output. Put in a monthly rent you would accept and see what it produces. If the case only works at ₹25,000, ask what happens at ₹18,000.
Use the all-in cost. Registration at 7.5 per cent and the possession charges are not recoverable at exit.
Assume vacancy. One month a year is standard. In the completion window, when hundreds of identical flats list together, assume more.
Separate yield from appreciation. Residential in India has generally been an appreciation play with a modest income attached, not an income asset. Devanahalli rates moved from about ₹8,900 per square foot in late 2025 to about ₹9,250 to ₹9,550 by mid 2026. That is where the return has historically come from on this corridor.
Frequently asked questions
Roughly ₹19,000 to ₹25,000 a month as of mid 2026, with listing averages near ₹23,000. These are asking rents in a thinly listed market, so achieved rents can be lower.
On a Parklane 1 BHK costing about ₹72.4 lakhs all in, gross yield runs about 3.0 to 4.1 per cent. Net of maintenance and a month's vacancy, it is closer to 2.3 to 3.3 per cent.
It is the main risk to a rental model here. The units share one layout and complete together, so tenants gain pricing power and today's scarcity premium is unlikely to survive.
Mainly engineers and supervisors at the aerospace and electronics employers, along with airport and airline staff and young professionals. Line staff generally cannot support a ₹20,000 rent.
As an income asset the yield is modest, in line with Indian residential at 2 to 4 per cent net. The case rests mainly on appreciation on a corridor with committed infrastructure spending.
Not on a typical 80 per cent loan. At ₹23,000 a month, rent covers about 54 per cent of a ₹42,689 EMI, leaving roughly ₹22,500 a month to fund from your own income.
At ₹23,000 rent, roughly 62 per cent of the price. That shrinks the loan to about ₹24.5 lakhs, whose EMI plus maintenance the rent can cover.
About ₹2,855 a month on 571 sq ft, at the fact sheet's ₹5 per sq ft. That is normally the owner's cost, so it comes off your rental income.