Blogs
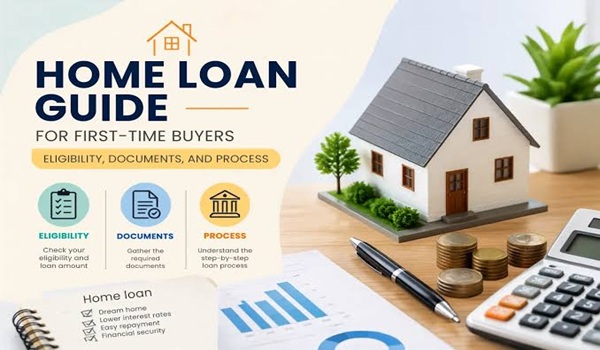
Home loan eligibility for new launch apartments depends on income, credit score, job type, and the project's RERA status. The process involves document checks, property checks, and staged payouts as construction moves ahead. Most banks avoid full payout until RERA registration is complete. This is because new launch projects often lack this approval at the booking stage.
Prestige Parklane, a new launch project by Prestige Group in Devanahalli, is a useful example. It is registered with Karnataka RERA under PRM/KA/RERA/1251/309/PR/150926/008941, and construction begins on 01 October 2026. Buyers who are interested in Prestige Parklane need to understand how loan eligibility works and how much the bank will release at each stage of construction.
This knowledge is useful before you file an EOI or pay the allotment amount.
There are a few things a bank will always check before giving you the loan. Your monthly income is the biggest factor in determining the loan amount. Solid employment and business history make an application stronger too.
Generally, having a credit score over 750 can give you better chances of getting approved and better loan terms. Outstanding debts also play a role when calculating the maximum amount you are eligible for. The age and the period of repayment together determine the maximum loan term.
That, of course, is incomplete now since RERA registration also affects approval status for new launch. Most lenders require the project to have an active RERA registration prior to sanctioning the loan. Otherwise, the banks could sanction the loan, but will not disburse fully.
Prestige Parklane is registered with Karnataka RERA under PRM/KA/RERA/1251/309/PR/150926/008941. Buyers should verify loan conditions with their bank prior to booking any unit.
Applicants need standard KYC documents, income proof, and property-related paperwork for approval.
These documents are PAN card, Aadhaar card and latest salary slips/ITR filing. Self‑employed applicants usually submit business proof. Audited financial statements instead. Bank statements for the past six months are also requested.
Buyers need the booking agreement, payment receipts and the builder's title documents. The RERA registration certificate must be submitted as well. Banks might also ask the developer directly for the sanctioned building plan.
Disbursement for launch apartments normally takes place in steps that match the construction progress. Banks give out money only after they confirm that the builder has achieved each construction milestone. This disbursement protects the buyer and the lender from risk.
For Prestige Parklane, possession is set for 31 December 2030, more than four years away. This means disbursement will stretch across a long construction timeline.
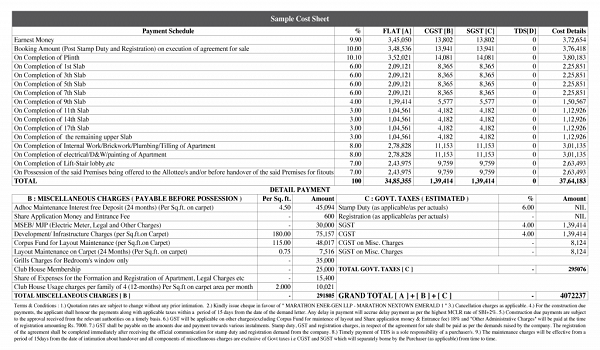
Prestige Parklane uses a date-linked payment plan: 10% at allotment, 10% at the sale agreement, then 24 instalments of 3.2% each every two months from 10 December 2026 to 10 October 2030, and a final 3.2% on intimation of possession on 31 December 2030, when the other charges also fall due. GST is added to every payment. Instalments fall due on set dates rather than at construction stages, while banks usually release loan money against certified construction progress. Buyers should plan to cover any gap between an instalment falling due and the bank releasing its share.
Banks are hesitant because of project risk. This hesitation continues until RERA registration and all approvals are completed. Any construction delays or legal issues can push back the builder's delivery timeline. Lenders carefully review the developer's track record before approving any loan exposure.
A strong brand like Prestige Group, with over 300 completed projects, eases this hesitation. Still, banks usually wait for RERA registration before a full loan commitment starts.
Buyers need to check the project's RERA status directly using the Karnataka RERA portal first. Looking at loan offers from banks can help get better interest rates.
Making sure the builder has a reputation and a history of delivering on time lowers the risk of problems later. Buyers also need to read the payment schedule carefully before signing any agreement.
Yes, most banks would rather wait until RERA registration is finished.
A score above 750 usually makes it easier to get a home loan. Can lead to better loan terms.
Most lenders need RERA registration, although a few may give approval before registration is finished.
The loan is given in stages matching the builder's construction milestones over time.
Phase 1 is RERA registered under PRM/KA/RERA/1251/309/PR/150926/008941.