Prestige Estates Projects Stock Report: Strong Growth Forecast, Debt in Focus
Prestige Estates Projects Limited (NSE: PRESTIGE) carries a market cap of Rs 613.4 billion. Analysts see strong growth ahead. This comes even after a mixed run of past earnings. Here is a clear look at where the stock stands today.
Future Growth: Strong Forecasts Ahead
Prestige Estates meets 4 out of 6 future growth checks used by analysts. The firm is set to grow earnings by 32.3% a year. Revenue should grow by 18.6% a year. Both numbers beat the wider Real Estate industry's earnings growth rate of 24.2% a year.
| Metric | Value |
|---|---|
| Earnings growth rate | 32.3% per year |
| EPS growth rate | 31.85% per year |
| Revenue growth rate | 18.6% per year |
| Real Estate industry earnings growth | 24.2% per year |
| Future return on equity (3 years) | 13.48% |
| Analyst coverage | Good |
| Last updated | 09 Sep 2026 |
Analyst estimates have moved often this year. In November, EPS forecasts for FY26 rose 12%. Revenue guidance rose too, to Rs 116.9 billion. Days later, EPS estimates rose again. This time, the revenue forecast dipped a bit. In August, EPS forecasts fell 12%, while revenue guidance rose. These shifts happen fast. New project launches and fresh reports keep changing the picture.
The consensus price target has moved between Rs 1,844 and Rs 1,934 across these updates. This range gives you a sense of where analysts see fair value today.
Past Performance: A Mixed Track Record
Prestige Estates meets 4 out of 6 past performance checks. Earnings have fallen at 12.2% a year on average. The wider Real Estate industry grew earnings by 23.7% a year over the same span. Revenue tells a better story. It grew at 9.6% a year.
| Metric | Value |
|---|---|
| Earnings growth rate (past) | -12.21% per year |
| EPS growth rate (past) | -13.64% per year |
| Real Estate industry growth | 20.39% per year |
| Revenue growth rate | 9.64% per year |
| Return on equity | 7.56% |
| Net margin | 8.73% |
| Last earnings update | 30 Jun 2026 |
Recent quarters show real strength, despite the earnings dip. In the full year 2026 results, EPS came in at Rs 27.76. That is up sharply from Rs 11.19 in FY25. Revenue rose 73% to Rs 126.9 billion. Net income climbed 156% to Rs 12.0 billion. Revenue beat analyst estimates by 2.7%. EPS missed estimates by 7.7%, though.
The third quarter of FY26 told a similar story. EPS reached Rs 5.17, up from just Rs 0.41 a year earlier. Revenue jumped 129% to Rs 38.9 billion. This beat analyst forecasts by 35%. Such swings are common for real estate firms. Large launches and sales can move numbers fast.
One point stands out. Over the last three years, EPS has fallen 21% a year on average. Yet the share price has climbed 43% a year over the same stretch. This gap hints that the market prices in future growth, not just past earnings.
Financial Health: Debt Remains a Watch Point
Prestige Estates meets only 2 out of 6 financial health checks. This is its weakest score among the areas tracked here.
| Metric | Value |
|---|---|
| Debt to equity ratio | 105.49% |
| Total debt | Rs 176.59 billion |
| Total shareholder equity | Rs 167.40 billion |
| Total assets | Rs 733.68 billion |
| Total liabilities | Rs 566.28 billion |
| Interest coverage ratio | 2.4x |
| Cash and short-term investments | Rs 32.80 billion |
A debt-to-equity ratio above 100% means the firm carries more debt than equity. This is common for real estate builders. They often borrow heavily to fund land and construction. Still, the interest coverage ratio sits at 2.4x. This means the firm can cover its interest payments from operating earnings. The margin here is not wide, though.
What This Means on the Ground
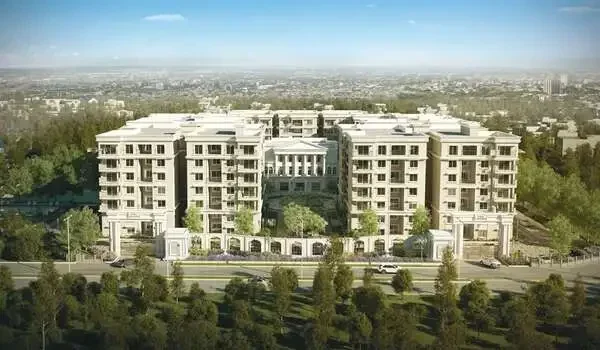
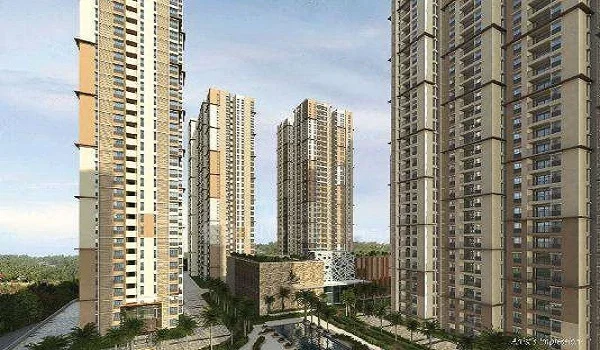
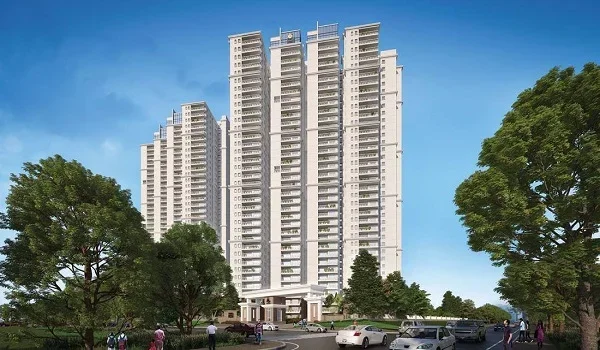
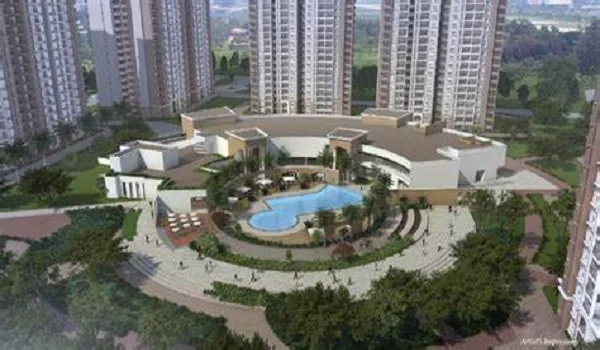
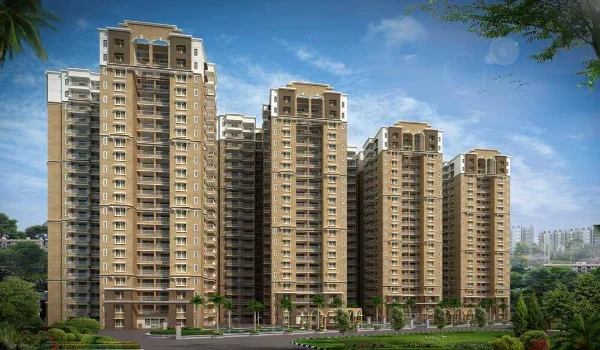
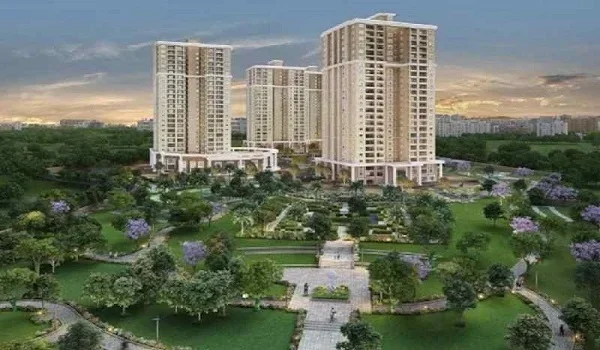
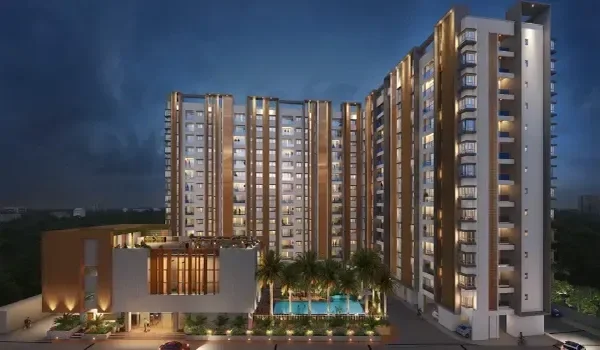
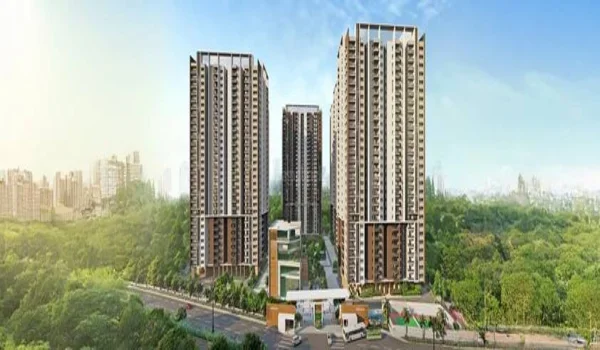
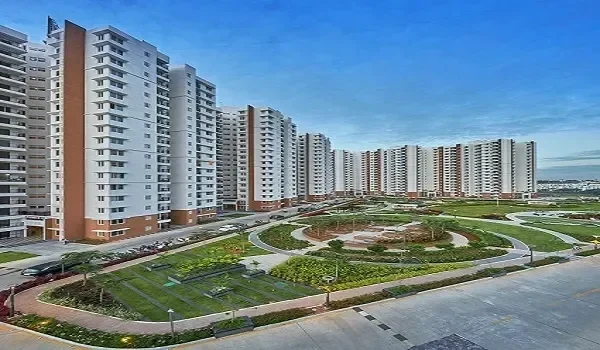
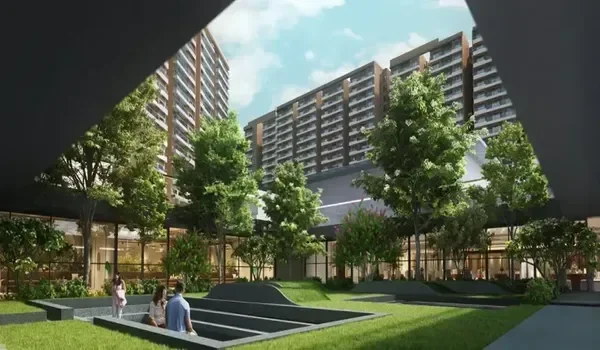
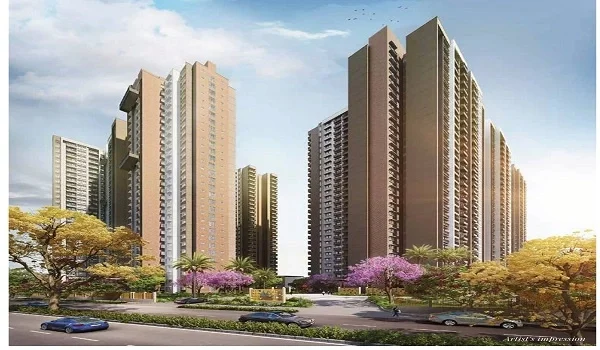
Numbers on a balance sheet tell only part of the story. Prestige Group funds its growth through active launches. These span South India and newer markets like Delhi-NCR. Projects such as Prestige Parklane in Devanahalli show where this money goes. The project spans over 32 acres. It offers 1,788 homes across nine towers, with prices starting from Rs 65 lakh.
Large launches like this explain the debt load on the balance sheet. They also explain why analysts keep revising growth forecasts. Projects like Prestige Parklane move from launch to sale to construction fast. If this pipeline turns into steady sales, the current debt looks more like growth capital than risk.
Should You Watch This Stock?
Prestige Estates fits a familiar pattern for a growing Indian real estate firm. It shows strong forecast growth. It runs a debt-funded expansion. Its earnings swing sharply between quarters. The stock has rewarded patient holders. Its share price rose 43% a year on average over three years, even as EPS fell over that time.
If you track Prestige Group's stock, watch three things ahead. First, check if new launches, like the Gurgaon Sector 109 project and Bengaluru townships, turn into steady revenue. Second, watch if the debt-to-equity ratio falls as projects like Prestige Parklane complete and sell out. Third, track whether analyst EPS estimates settle down after a year of frequent changes.
This analysis uses data from S&P Global Market Intelligence and Simply Wall St, current as of September 2026. It offers general information, not financial advice. Speak with a licensed financial advisor before you make any investment decision.
FAQs
The company carries a market cap of Rs 613.4 billion as of September 2026.
Analysts forecast earnings growth of 32.3% a year and revenue growth of 18.6% a year over the coming years.
Earnings fell 12.2% a year on average in recent years, even as revenue grew 9.6% a year, reflecting swings tied to project timing.
Its debt-to-equity ratio stands at 105.49%, common for real estate builders, though its interest coverage ratio of 2.4x shows it can service this debt.
Prestige Parklane in Devanahalli is one of the large, active launches funding the growth and debt seen in these numbers.
No. This is general information, not financial advice. Speak with a licensed financial advisor before making any investment decision.